Why the Semiconductor Chip Boom Outpaces the Dot-Com Bubble, According to VanEck
VanEck expert Nick Frasse breaks down why the current semiconductor chip boom driven by the AI buildout differs fundamentally from the 2000 dot-com bubble.
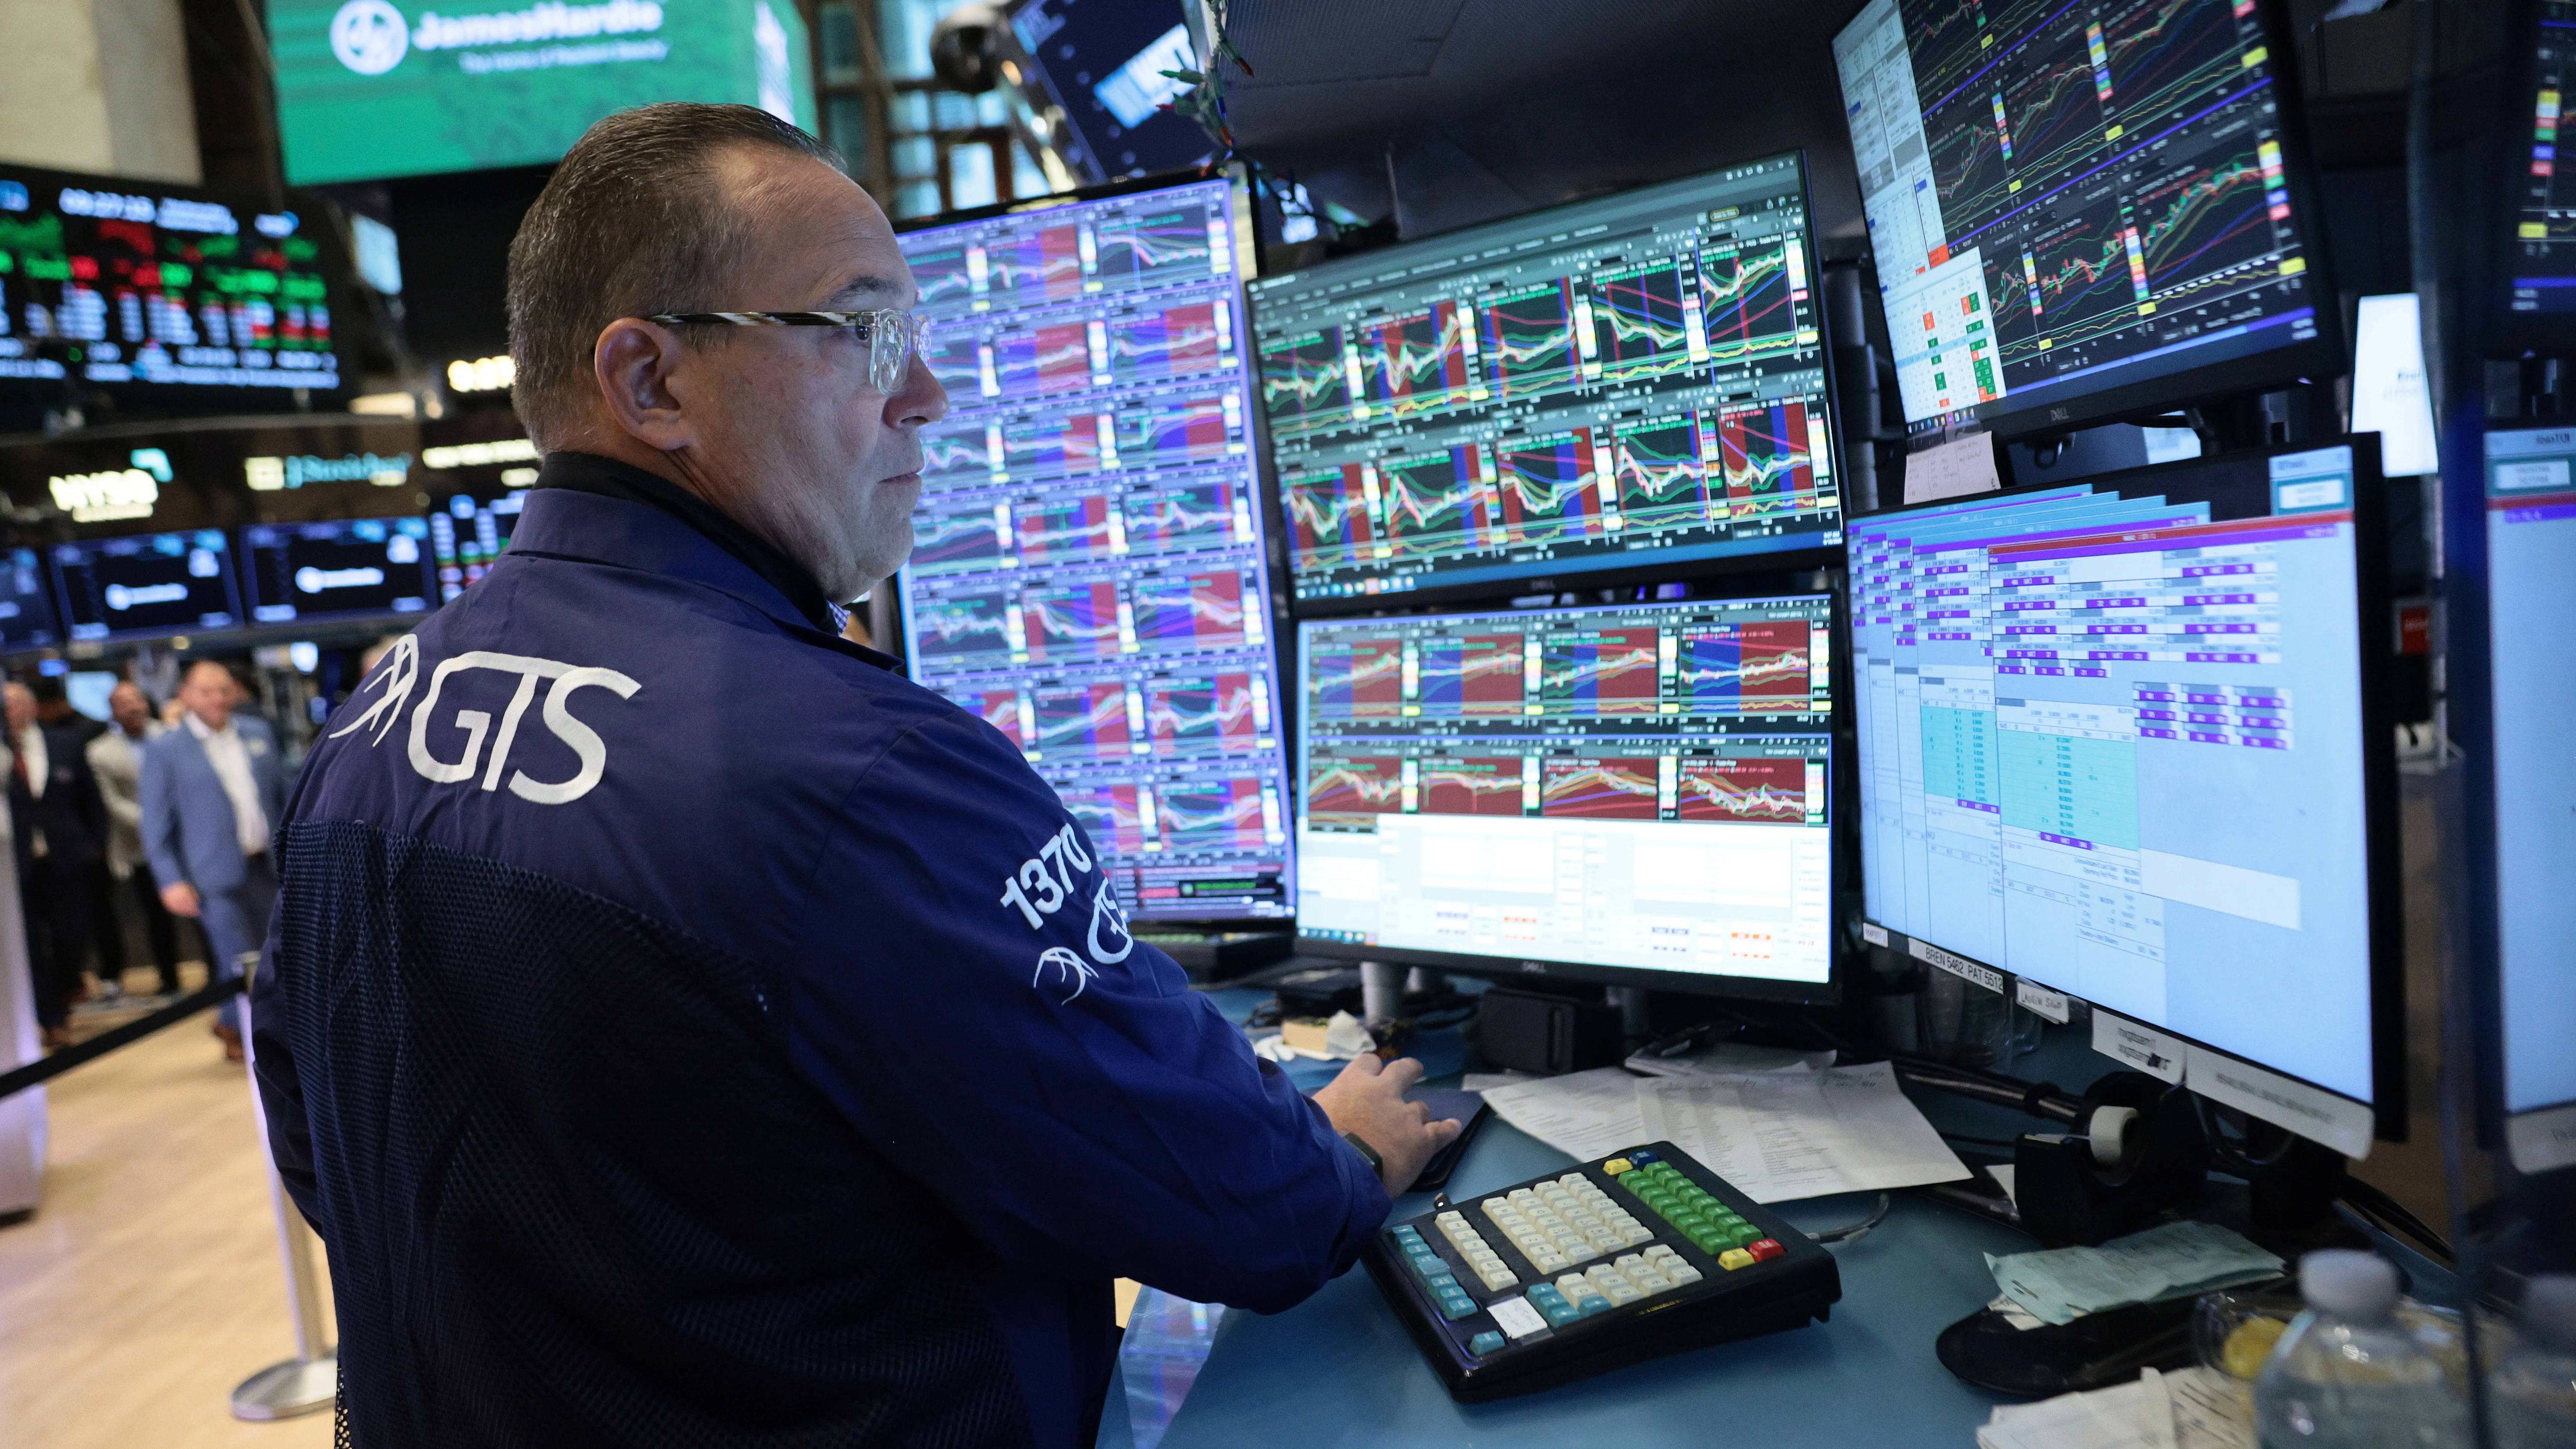
Source image: inc.com
inc.comUnderstanding the Current Chip Boom
The global semiconductor market has experienced unprecedented growth, largely catalyzed by the relentless demand for artificial intelligence infrastructure and advanced hardware. However, market observers frequently draw parallels to the dot-com bubble of 2000, warning of an impending market correction. Addressing these concerns during an appearance on Full Signal, VanEck expert Nick Frasse provided a comprehensive counter-narrative, explaining why today's semiconductor surge is fundamentally different from past speculative manias.
According to the insights shared by Frasse, the primary driver setting the current environment apart is the nature of the demand. While the dot-com era was characterized by speculative consumer-facing startups with little to no revenue, the modern chip boom is anchored by massive, profitable enterprise technology companies investing heavily in core infrastructure. These firms are building out data centers and computational capacity designed to support verifiable, revenue-generating artificial intelligence workloads.
Why Fundamental Differences Matter for Investors
For institutional investors, corporate executives, and entrepreneurs, distinguishing between a speculative bubble and a fundamental structural shift is vital for strategic planning. Frasse emphasized that major semiconductor manufacturers today boast strong balance sheets, high profit margins, and predictable cash flows. This financial resilience starkly contrasts with the high-burn, pre-revenue business models that dominated the late 1990s tech sector.
- Robust Balance Sheets: Leading chipmakers and tech giants finance expansions through existing cash reserves and strong operational cash flow rather than risky debt or speculative equity offerings.
- Tangible Utility: Semiconductors are currently bottlenecked by real-world demand across cloud computing, automotive industries, industrial automation, and generative AI deployment.
- Enterprise Adoption: Corporate buyers are integrating AI chips to drive operational efficiency, creating sticky, long-term enterprise software and hardware dependencies.
Broader Market Implications
The ongoing buildout of semiconductor supply chains carries profound implications for global markets. As hardware becomes the foundational layer of the modern digital economy, nations and corporations alike are viewing silicon independence and supply chain security as matters of national and economic strategy.
Entrepreneurs operating outside the core tech sector must recognize that artificial intelligence and advanced computing are transforming traditional industries. From healthcare diagnostics to supply chain logistics, the integration of high-performance chips is reshaping competitive advantages. Consequently, capital allocation strategies must account for hardware availability and the rising baseline cost of computational infrastructure.
What Readers Should Watch Moving Forward
To navigate the semiconductor landscape successfully, market participants should monitor specific indicators rather than succumbing to broad macro panic. Key areas to watch include:
- Enterprise Capital Expenditure: Tracking the ongoing capital expenditure announcements of major cloud service providers and tech conglomerates to gauge sustained demand.
- Supply Chain Bottlenecks: Evaluating manufacturing capacity expansions, advanced packaging availability, and raw material access across global fabrication hubs.
- Monetization Metrics: Observing how effectively end-users and software enterprises translate raw AI compute power into profitable business models and end-market revenue.
For more detailed insights and the complete discussion, read the original report on Inc.
Continue reading
Related coverage in Leadership
inc.com
Tate McRae Enters the Fragrance Market with Broad Trademark Strategy
Singer Tate McRae is expanding into the fragrance industry with a trademark that extends well beyond perfume, signaling ambitious multi-category brand growth ahead.
2 min read
inc.com
Oheka Castle Heads to Bankruptcy Auction with Strict Terms for Prospective Buyers
Famed Long Island estate Oheka Castle prepares for a Chapter 11 bankruptcy auction, requiring its next buyer to honor booked events extending all the way into 2028.
3 min read
inc.com
Evaluating Leadership Effectiveness: The Daily Question That Matters More Than Your Title
Discover how a single daily self-reflection question can redefine your leadership effectiveness and outperform traditional titles in driving organizational success.
3 min read
inc.com
Tesla Workplace Culture Put to the Test as Employee Complaints Spark Broad Leadership Debate
Tesla's workplace culture faces severe scrutiny, highlighting a critical leadership test regarding psychological safety and how organizations respond to employee complaints.
2 min read