Navigating the Equities Downturn: Why September Remains the Market’s Most Feared Month
As historical data flags September as the S&P 500's weakest month, investors weigh seasonal volatility against robust corporate earnings and macroeconomic tailwinds.
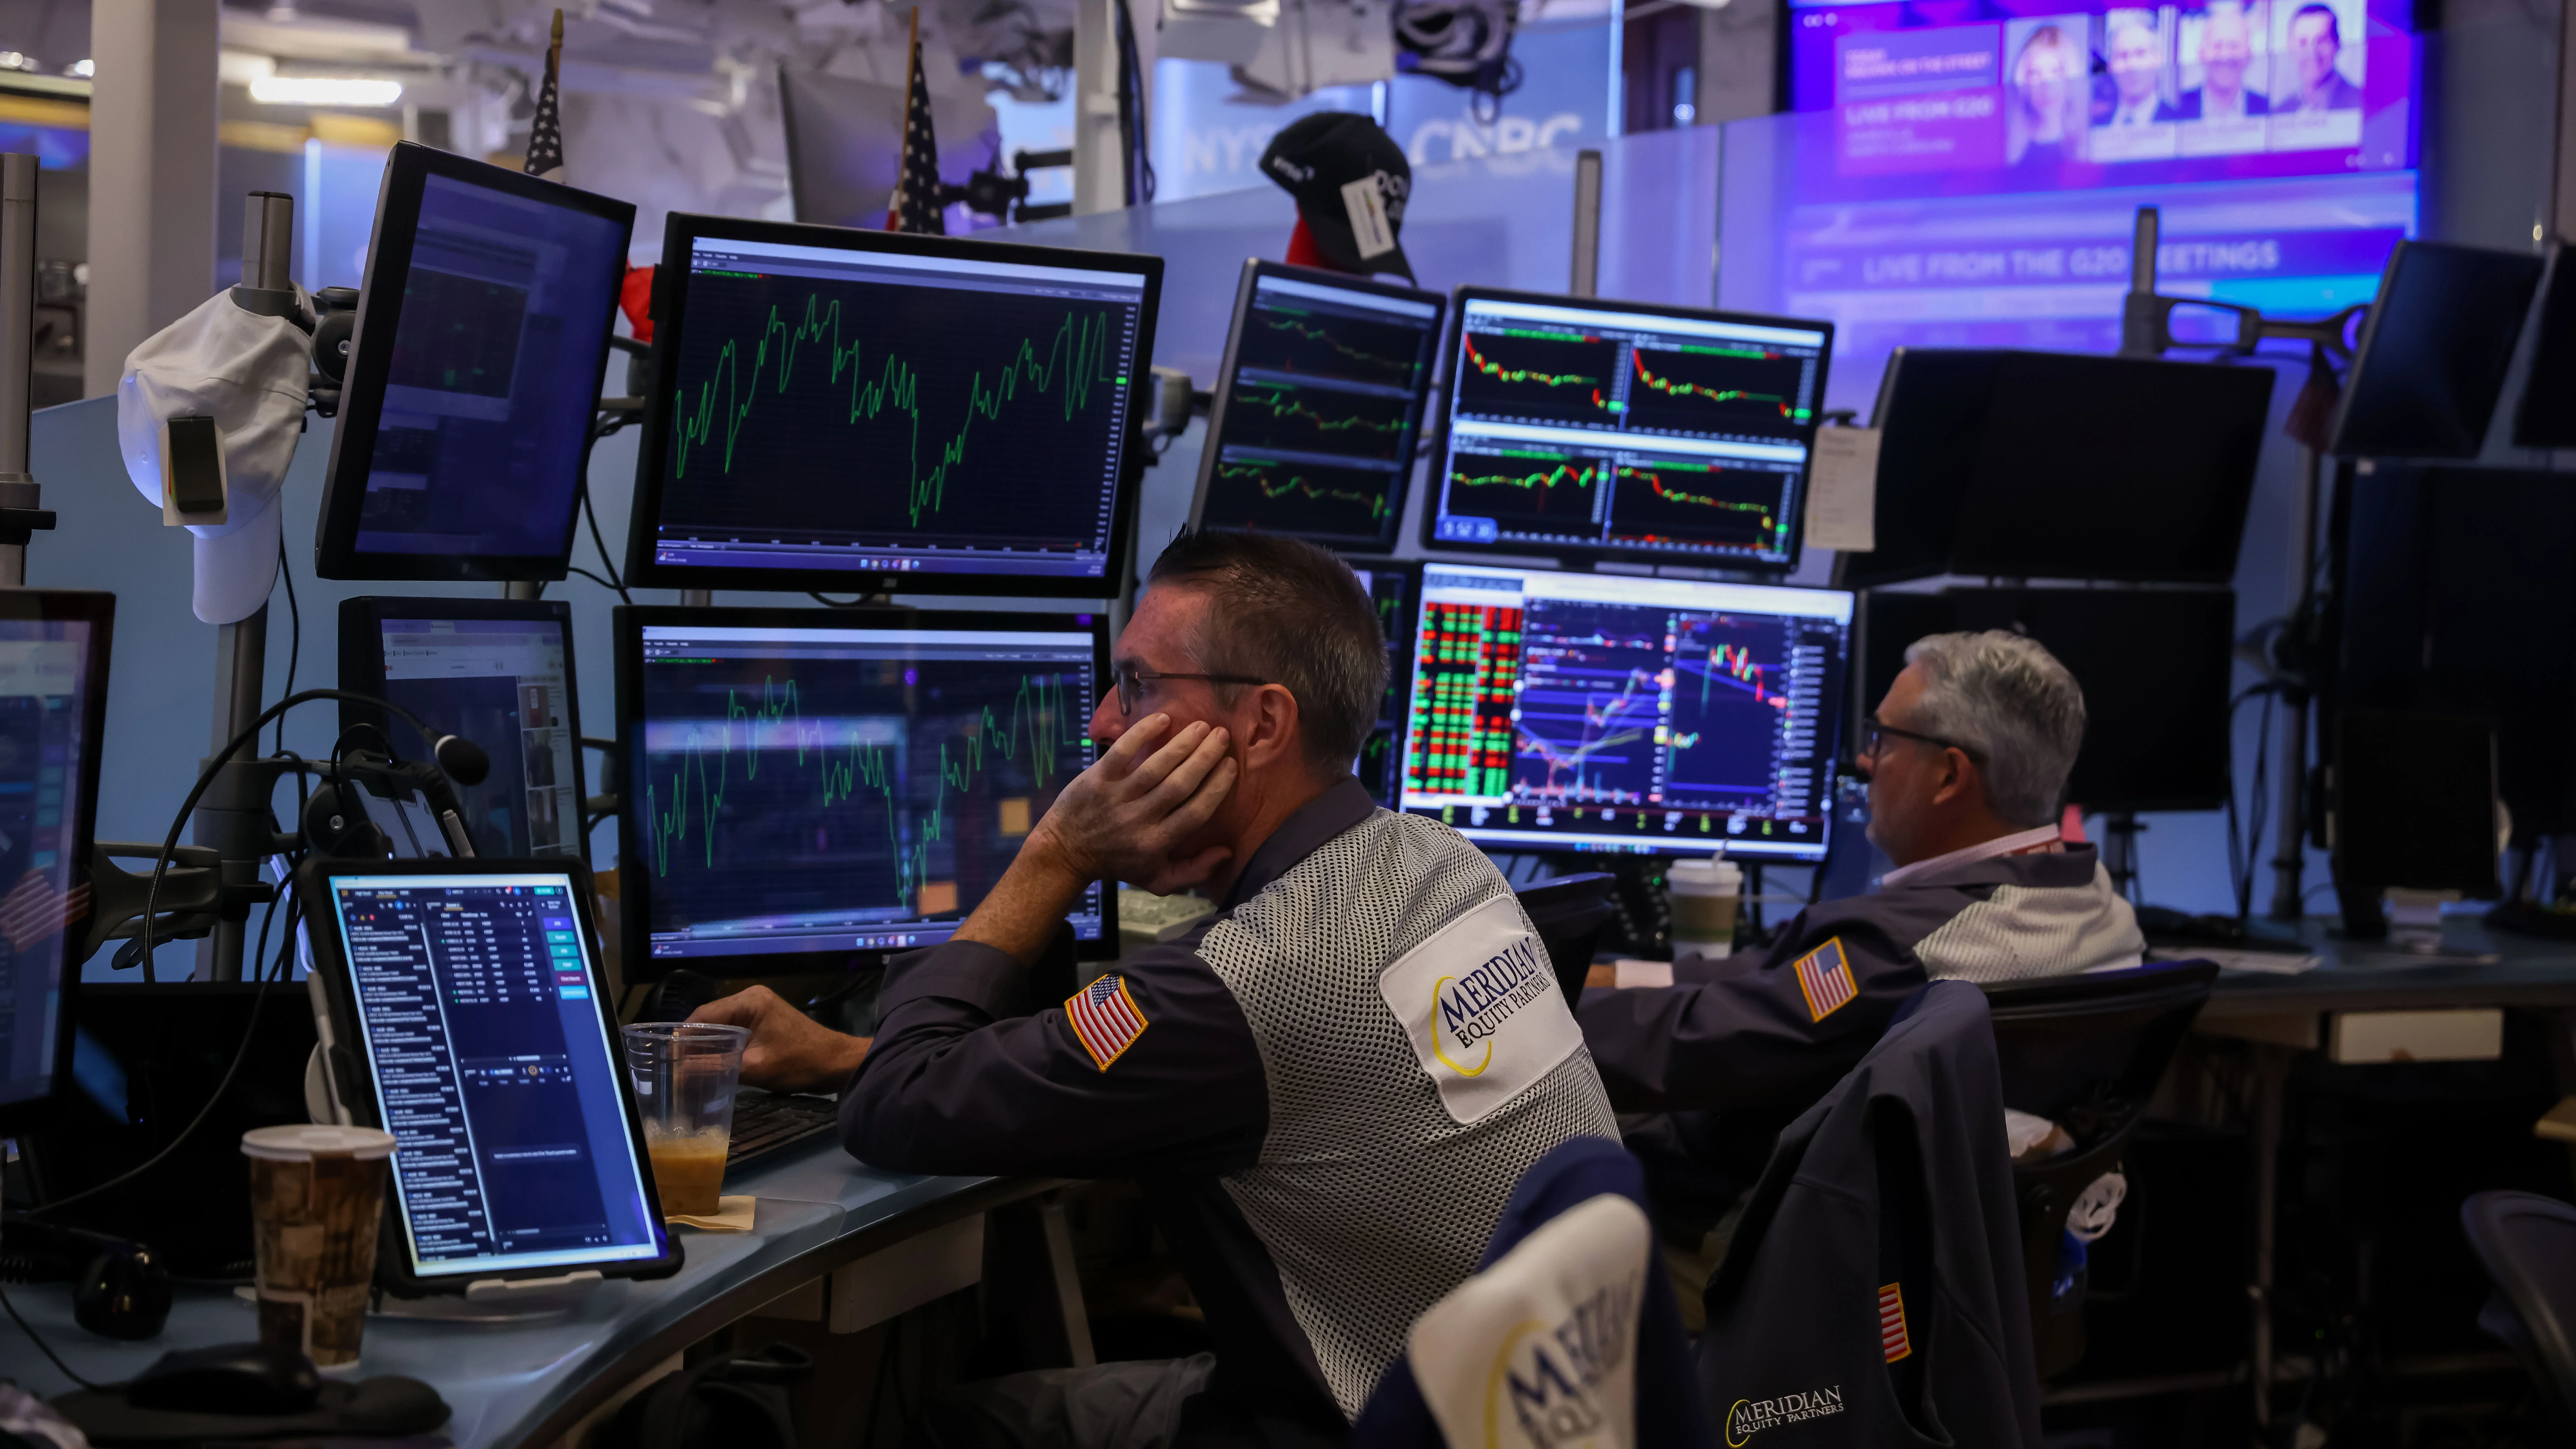
Source image: inc.com
inc.comUnderstanding the Historical Seasonality of September
For decades, Wall Street veterans have treated the late-summer and early-fall stretch with a degree of caution. Historical trading data spanning the last fifty years reveals that September stands alone as the only month where the S&P 500 regularly posts a negative average return, accompanied by a win rate hovering below fifty percent. When narrowing the historical scope to post-1990 data, both August and September average negative territory, cementing a reputation for seasonal sluggishness that tests even the most disciplined market participants.
However, modern financial markets do not operate in a vacuum of blind historical adherence. The onset of this seasonal hurdle arrives while corporate balance sheets remain remarkably sturdy. Net profit margins for the S&P 500 have hovered near multi-year highs, supported by robust revenue expansion across diverse sectors rather than just mega-cap technology anomalies. Executives and institutional allocators are therefore forced to balance the looming ghost of historical drawdowns against tangible, fundamental economic strength.
The Clash Between Market Resilience and Seasonal Headwinds
Defying conventional expectations, the broader market indices recently pushed through summer with powerful momentum, brushing off historical precedents that typically warn of mid-year fatigue. The sustained tailwind of the artificial intelligence infrastructure build-out, combined with a broadening market rally extending well beyond tech behemoths into financials, industrials, and healthcare, has kept major benchmarks near record territories.
Market strategists point out that entering September with a double-digit year-to-date gain fundamentally alters the risk profile. Historical distributions show that when the S&P 500 enters the autumn months on a strong upward trajectory following a positive August, the remaining months of the calendar year finish in the green the vast majority of the time. This statistical nuance suggests that seasonal weakness, when it does materialize, frequently serves as a short-term consolidation phase rather than the inception of a secular bear market.
Key Macroeconomic Indicators and Market Implications
For executive leadership teams and active investors, managing portfolios through this window requires monitoring several critical market drivers:
- Monetary Policy Shifts: Anticipation surrounding central bank interest rate decisions continues to dictate short-term sentiment, influencing borrowing costs and valuation multiples.
- Earnings Concentration vs. Broadening Participation: While top-tier mega-caps drive outsized headline earnings, equal-weight indices and blue-chip averages demonstrate that broader market health remains surprisingly resilient.
- Volatility and Liquidity: Reduced trading volumes during late August transitions can occasionally amplify intraday price swings as institutional desks react to macroeconomic data releases.
Understanding these variables helps separate structural economic shifts from routine calendar-driven volatility. While retail sentiment can occasionally overreact to short-term pullbacks, sophisticated market participants view seasonal dips as potential liquidity events.
Strategic Positioning for Investors and Entrepreneurs
For corporate decision-makers, founders, and capital allocators, navigating September's historical volatility demands a calculated approach. Rather than panic-selling into seasonal downdrafts, savvy investors frequently evaluate fundamental asset values to identify tactical entry points. Because historical data indicates that fourth-quarter rallies frequently follow corrective summer phases, liquid capital can often be deployed advantageously during periods of unwarranted macro-driven pessimism.
Ultimately, while the calendar points to a historically difficult month, prevailing corporate fundamentals tell a story of structural resilience. Market participants who maintain a long-term horizon, focus on underlying enterprise profitability, and look past short-term noise will be best positioned to capitalize on whatever autumn volatility unfolds.
Continue reading
Related coverage in Business
nytimes.com
David Ellison Targets CNN Leadership Continuity in Paramount Merger Talks
David Ellison is currently negotiating to retain CNN CEO Mark Thompson without oversight from CBS editor in chief Bari Weiss as parent companies navigate merger plans.
2 min read
bbc.com
Decoding Nike’s Slump: How Strategic Missteps Cost the Sportswear Titan Its Edge
Explore the factors behind Nike's dramatic market decline. Industry analysts dissect the self-inflicted strategic errors that shook the sportswear giant.
3 min read
bbc.com
Treasury Committee Directs HMRC to Investigate Tax Implications of Manchester City Case
The UK Treasury Committee has called on HMRC to closely examine potential tax ramifications arising from the high-profile Manchester City legal verdict.
3 min read
nytimes.com
US Imposes Sanctions on Russian Firm A7 Over Global Shell Company Evasion Schemes
The United States targets Russian financial firm A7 with new sanctions following reports of utilizing global shell companies to bypass existing economic restrictions.
3 min read