Crude Oil Breaches $100 Threshold as Middle East Tensions and Supply Disruptions Escalate
Global benchmark Brent crude surged past $100 a barrel as intensifying military conflicts in the Middle East heighten severe energy supply concerns.
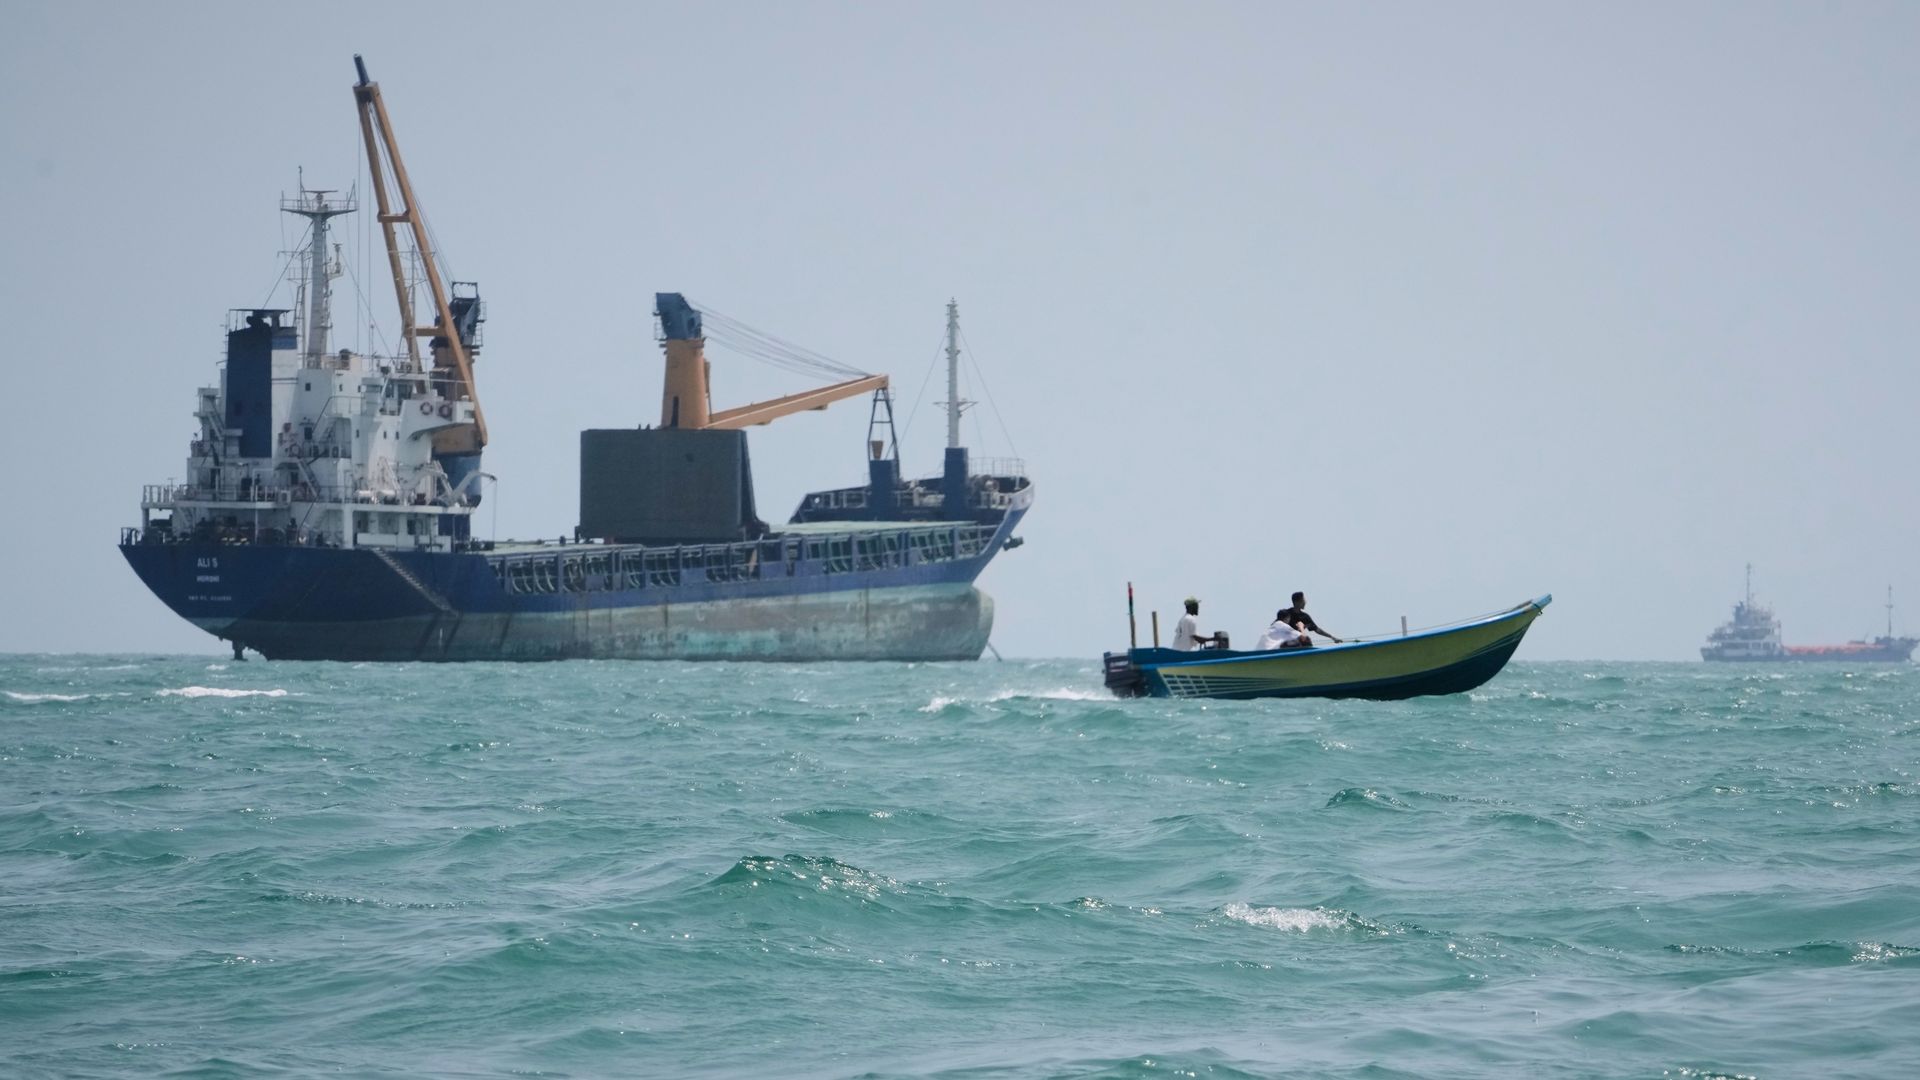
Source image: skynews.com
skynews.comGeopolitical Tensions Drive Crude Past the $100 Milestone
Global energy markets reached a critical inflection point as benchmark Brent crude oil futures climbed past the symbolic $100-per-barrel threshold. This movement marks the highest price level observed since late July, propelled by an aggressive escalation in Middle Eastern military hostilities that have placed vital petroleum export routes directly in the crosshairs.
The immediate catalyst for the sharp upward trajectory stems from a compounding series of security incidents across the Persian Gulf and the Red Sea. Recent exchanges involving naval forces and strategic energy infrastructure have severely disrupted the flow of hydrocarbons from the world's most critical supply hub. Market participants are increasingly pricing in a prolonged structural deficit as diplomatic efforts stall.
Anatomy of the Supply Crunch
At the heart of the current crisis is the protracted stalemate in the multi-month conflict involving the United States and Iran, which has severely restricted maritime transit through the Strait of Hormuz. Compounding these pressures, recent regional strikes targeting energy installations in Saudi Arabia and surrounding areas have threatened secondary export routes via the Red Sea corridor.
Key supply factors impacting the market include:
- Strait of Hormuz Restrictions: Persistent blockades and military friction have dramatically curtailed tanker throughput compared to historical baselines.
- Infrastructure Vulnerabilities: Recent drone and missile strikes targeting regional processing facilities have stoked fears of physical supply destruction.
- Depleted Spare Capacity: With major producers operating under strained conditions, global spare production capacity buffers are running dangerously thin.
- Upward Revisions by Wall Street: Leading global financial institutions, including major investment banks, have rapidly adjusted their near-term crude price projections upward.
Macroeconomic Implications and Central Bank Dilemmas
The resurgence of triple-digit oil prices presents a severe complication for central banks worldwide, including the U.S. Federal Reserve. Just as policymakers began mapping out paths toward monetary easing, surging energy costs threaten to reignite headline consumer price inflation. Sustained high fuel prices invariably ripple through supply chains, escalating transportation costs and manufacturing overhead.
Economists warn that if energy prices remain elevated or climb further toward the peaks observed earlier in the year, central banks may find themselves forced to maintain restrictive interest rates longer than anticipated. This scenario risks dampening broader economic growth equity markets as corporate margins absorb higher input costs.
Strategic Outlook for Investors
For institutional investors, corporate executives, and energy sector traders, the current environment demands heightened vigilance. Navigating this volatility requires closely monitoring several critical indicators over the coming weeks:
Investors should closely track the evolution of maritime security arrangements in the Gulf, official output adjustments from non-OPEC producers compensating for regional losses, and upcoming central bank commentary regarding inflation expectations. Asset allocation strategies should account for sustained energy sector outperformance juxtaposed against potential headwinds in consumer discretionary and manufacturing sectors.
Continue reading
Related coverage in Business
nytimes.com
David Ellison Targets CNN Leadership Continuity in Paramount Merger Talks
David Ellison is currently negotiating to retain CNN CEO Mark Thompson without oversight from CBS editor in chief Bari Weiss as parent companies navigate merger plans.
2 min read
bbc.com
Decoding Nike’s Slump: How Strategic Missteps Cost the Sportswear Titan Its Edge
Explore the factors behind Nike's dramatic market decline. Industry analysts dissect the self-inflicted strategic errors that shook the sportswear giant.
3 min read
bbc.com
Treasury Committee Directs HMRC to Investigate Tax Implications of Manchester City Case
The UK Treasury Committee has called on HMRC to closely examine potential tax ramifications arising from the high-profile Manchester City legal verdict.
3 min read
nytimes.com
US Imposes Sanctions on Russian Firm A7 Over Global Shell Company Evasion Schemes
The United States targets Russian financial firm A7 with new sanctions following reports of utilizing global shell companies to bypass existing economic restrictions.
3 min read